Last updated: 16 October 2026
MOLIM is the official app and website of SIMAH, the Saudi Credit Bureau, for checking your own credit report and credit score. Your first report is free if you have never generated one before. After that, a one-time credit score costs SR 17.25, a one-time credit report SR 28.75, and daily monitoring SR 40 a month or SR 336 a year, all including VAT. Expats register with their Iqama number through Nafath.
If you plan to apply for a personal loan, credit card, car finance, or home financing in Saudi Arabia, your credit score will influence the outcome long before a bank officer reviews your application. Lenders in the Kingdom pull this number from a single national source, and checking it yourself takes only a few minutes once you know where to look.
What Is a Credit Score in Saudi Arabia?
Personal credit reports in Saudi Arabia come from SIMAH, the Saudi Credit Bureau, licensed by the Saudi Central Bank (SAMA). Bayan, the other licensed bureau, covers companies, not individuals. SIMAH collects data on how residents and citizens manage credit, covering loan repayments, credit card usage, financing agreements and payment history, then turns it into a three-digit score.
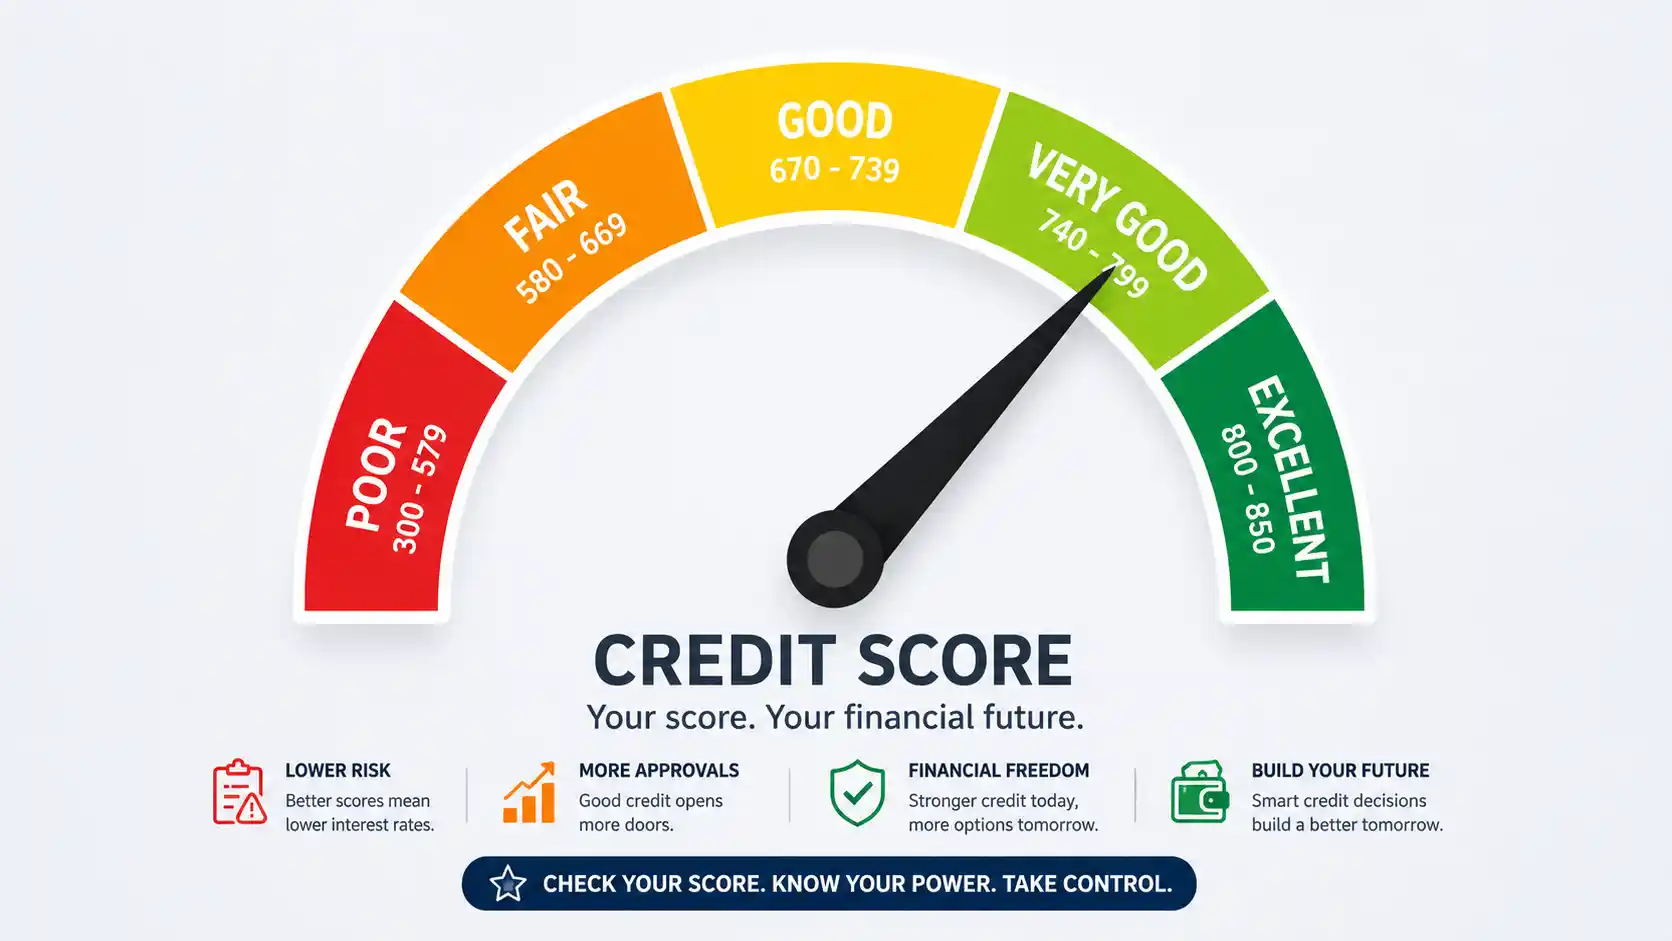
MOLIM is SIMAH’s consumer platform. It is the app individuals use to view their own score and credit report rather than going through a bank. Every MOLIM credit score is a three-digit number between 300 and 850, powered by FICO, and SIMAH data is used by banks, finance companies, telecom providers, insurers and some government entities to gauge financial risk.
In short: SIMAH holds the data, and MOLIM is how you access it as an individual.
Follow Saudi Life Guide for Iqama, visa and job updates
New rules, fees and news as soon as we publish them. Join 60,000+ followers on Facebook.
SIMAH Credit Score Ranges Explained
The table below shows how credit scores are generally interpreted in the Saudi lending market. These bands are not an official SIMAH classification published with fixed labels, but they reflect how most lenders in KSA read the 300 to 850 scale in practice.
| Score Range | Rating | What It Typically Means |
|---|---|---|
| 750 to 850 | Excellent | Strong approval odds, best interest rates |
| 650 to 749 | Good | Eligible for most standard loan and card products |
| 550 to 649 | Fair | May face tighter terms, lower limits, or extra checks |
| 300 to 549 | Poor | Limited access; may need secured or credit-builder products |
Every lender sets its own internal cut-off, so two banks can treat the same score differently. A higher score generally means faster approval and better pricing, but it does not guarantee approval on its own. Lenders also look at income, existing debt and employment status.
Which bank you apply to matters as much as the score itself. Our guide to the best banks in Saudi Arabia for expats covers which lenders are more accommodating on expat applications and what each typically requires.
How to Register for MOLIM and Check Your Credit Score
Checking your score for the first time involves five steps:
- Download the MOLIM app from the Apple App Store or Google Play Store, or go to molim.sa and fill in the Nafath form with your National ID or Iqama number.
- Open the app and tap Register.
- Enter your Iqama number if you are a resident, or your National ID if you are a Saudi citizen.
- Verify your identity through Nafath, Saudi Arabia’s national digital identity app. This step confirms you are the account holder before any credit data is released.
- Log in once verification is complete. Your score and report become available immediately, subject to the package you choose.
If you do not already have Nafath set up, register there first, because MOLIM will not complete identity verification without it. Our Absher registration guide shows how to activate Nafath.
MOLIM Packages and Pricing
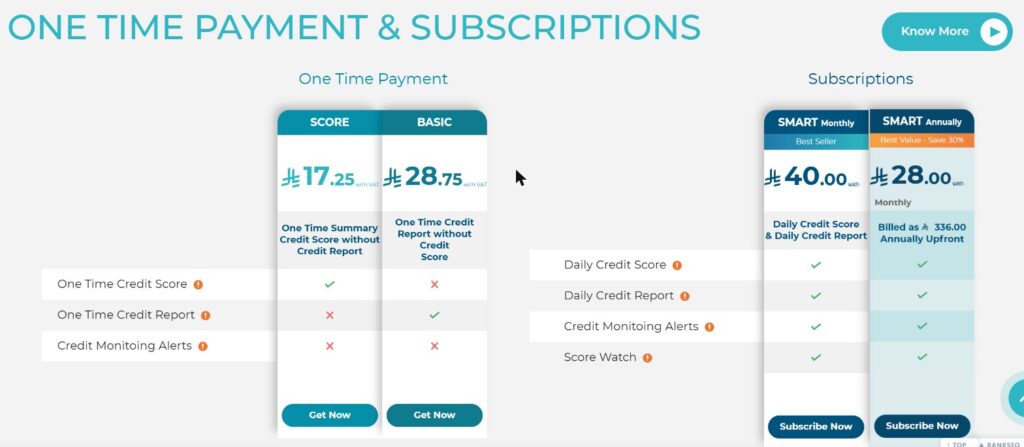
Your first credit report on MOLIM is free if you have never registered with SIMAH or generated a report or score before. After that you choose a one-time check or a subscription. These are the official prices on molim.sa in October 2026, including VAT:
| Package Type | What’s Included | Price |
|---|---|---|
| First-time user report | One free score and report | Free, once only |
| SCORE (one-time) | Credit score only, no report | SR 17.25 |
| BASIC (one-time) | Credit report only, no score | SR 28.75 |
| SMART Monthly | Daily score and report, alerts, Score Watch | SR 40 a month |
| SMART Annually | Same as SMART Monthly | SR 336 a year (SR 28 a month) |
If you only need to show a bank your standing once, BASIC (the report) is usually enough. Choose SMART only if you want to watch your score while you repair it.
First-time users, meaning anyone who has never generated a SIMAH report or score before, usually qualify for one free report. After that trial you will need to select a paid package to keep checking, whether that is a single one-off report or a subscription for ongoing monitoring.
What Your MOLIM Credit Report Includes
A MOLIM report gives you far more than a number. Once logged in, you can review:
- Your credit score, the 300 to 850 figure lenders reference
- Full credit report, a detailed history of your credit behaviour
- Active loans and financing, every open agreement linked to your ID
- Credit cards issued in your name, along with their limits
- Outstanding balances, what you currently owe across accounts
- Payment history, a record of on-time and late payments
- Credit inquiries, a log of which banks or finance companies have checked your file, and when
This breakdown is useful even if you are not applying for anything right now. It gives you a clear picture of your total exposure and flags anything that looks wrong before a bank finds it.
Why Your Credit Score Matters in Saudi Arabia
Banks and finance companies routinely check your SIMAH record before approving personal loans, credit cards, car finance or mortgages. Your score and report tell them how reliably you have handled credit in the past, which directly affects both approval odds and the terms you are offered: interest rate, credit limit and repayment period.
For expats specifically, your credit history starts from zero here. It builds over time from local accounts and financing, and it does not transfer from your home country. Salary transfer arrangements, timely bill payments and existing bank relationships all factor into how your score develops in the Kingdom.
Even if you are not planning to borrow soon, checking your report periodically helps you catch inaccuracies before they cost you an approval. A loan you settled months ago that still shows as active is a common example, and it will reduce your apparent capacity to borrow until someone corrects it.
What Affects Your Score
The main inputs are payment history, how much of your available credit you are using, how many active accounts you hold, and how recently you have applied for new credit.
Buy now, pay later counts. BNPL agreements are now regulated by SAMA and reported like other credit products, so they appear on your file. Following the increase in BNPL limits to SAR 10,000, it is easier than it was to accumulate obligations that show up on a SIMAH report without feeling like borrowing at the time.
Frequent applications hurt. Every formal application generates an inquiry that other lenders can see. Several within a short window reads as financial pressure, whether or not that is the case.
How to Improve Your SIMAH Credit Score
Improving your score comes down to consistent habits rather than any quick fix:
- Pay instalments on time. Payment history is the single biggest factor in your score.
- Keep credit utilisation low. Using a small percentage of your available limit reflects better than maxing out cards.
- Avoid applying for multiple credit products in a short window. Frequent inquiries signal financial stress to lenders.
- Settle overdue balances before applying for new financing. Outstanding unpaid amounts weigh heavily against you.
- Check your report periodically. Catching an error early prevents it sitting on your file for months.
None of this changes your score overnight. SIMAH updates records as lenders report new data, so improvements typically show up gradually over several billing cycles.
How to Dispute an Error on Your Credit Report
If you spot something incorrect on your MOLIM report, whether that is a loan you never took, a balance already settled, or a payment marked late that was not, you can raise a dispute.
Log in at eservices.molim.sa, open Disputes, fill in the form and attach your documents, such as a settlement letter or bank statement. MOLIM processes disputes within 30 working days at most, and you can track the status in the same account. You can dispute in five cases: a lender did not update your record within a week of settlement; the information is inaccurate, incomplete or wrong; negative information stays beyond the legal retention period; a lender checked your report without your consent; or a bounced cheque that you have already settled.
Data cannot be deleted from your report, only corrected, but you can add your own comment to it. If a lender rejects your credit application, it must tell you the reasons when you ask. MOLIM’s toll-free number is 8003010046, Sunday to Thursday, 8 am to 4:30 pm.
Start the dispute before you apply for anything. A month-long investigation running in parallel with a loan application does not help you, because the lender sees the file as it stands today.
Documents You Need Before You Start
Have these ready so registration goes through on the first attempt:
- Iqama number (residents) or National ID number (Saudi citizens). It must match the one on file with Absher.
- An active Nafath account, since MOLIM verification runs through it. If you have not set up Nafath, do that first through the Absher-linked registration process.
- A Saudi mobile number registered to your ID, for the OTP step during Nafath verification. If your number is not registered against your iqama, see our guide to registering a mobile number with your iqama.
- A payment method (mada, credit card, or Apple Pay where supported) if your free first-time report has already been used.
Having these ready avoids the most common registration failure: an identity mismatch between the ID number entered in MOLIM and the one linked to your Nafath account.
MOLIM vs Checking Through Your Bank
Some banks in Saudi Arabia display a version of your SIMAH score inside their own mobile banking app, usually when you apply for a loan or card. This is not the same as checking directly through MOLIM.
| MOLIM (SIMAH’s own app) | Bank app | |
|---|---|---|
| Full credit report access | Yes | Usually limited or not shown |
| Available without applying for a product | Yes | No, usually tied to an active application |
| Cost | Paid after the free first report | Often free, but incomplete |
| Shows inquiries from other lenders | Yes | Not usually |
If you only want a general sense of your standing, a bank app snapshot may be enough. If you want the full picture, meaning every account, every inquiry and every balance, MOLIM is the more reliable source because it is the platform SIMAH itself controls.
Final Thoughts
Checking your credit score in Saudi Arabia is a five-minute task once Nafath is set up: download MOLIM, verify your identity, choose a package. Given how much it affects both loan approval and pricing, it is worth reviewing your report before you apply for anything rather than after a rejection.
Before you apply for financing
FAQs
Is checking your credit score in Saudi Arabia free?
Your first MOLIM credit report is free if you have never registered with SIMAH or generated a report or score before. After that it is paid: SR 17.25 for a one-time score, SR 28.75 for a one-time report, or SR 40 a month for daily monitoring, all including VAT.
How much does a MOLIM credit report cost?
On molim.sa in October 2026, a one-time credit report (BASIC) costs SR 28.75 and a one-time credit score (SCORE) SR 17.25. The SMART subscription with a daily score, daily report and alerts costs SR 40 a month, or SR 336 a year paid upfront, which works out at SR 28 a month.
Can expats check their credit score in Saudi Arabia?
Yes. Any resident with a valid Iqama can register on MOLIM by filling in the Nafath form on molim.sa or in the MOLIM app, choosing a password and confirming a mobile number. Your credit history in Saudi Arabia starts here and does not transfer from your home country.
What is a good SIMAH credit score?
MOLIM scores run from 300 to 850, and a higher score means better credit health. SIMAH does not publish fixed bands, and each lender sets its own cut-off, but scores from about 650 upward are generally treated as good for standard loans and credit cards.
How long does a MOLIM dispute take?
MOLIM processes every dispute within a maximum of 30 working days. Submit it through your account at eservices.molim.sa under Disputes, attach documents such as a settlement letter, and track the status there. Start it before you apply for new credit, because lenders see your file as it stands.
Can I check if I am blacklisted in Saudi Arabia through MOLIM?
MOLIM does not show a “blacklist” status, but your report shows defaults, overdue balances, late payments and public records such as bounced cheques, which are what lenders look at. If a lender rejects you, it must explain the reasons when you ask.